AI-Powered Identity Verification & KYC/AML for Fintechs
Australian fintechs can use AI to speed up identity verification and KYC/AML screening during onboarding, but AUSTRAC obligations mean human review and clear audit trails remain essential. Here's how to balance automation with compliance.
What is AI-powered digital identity verification?
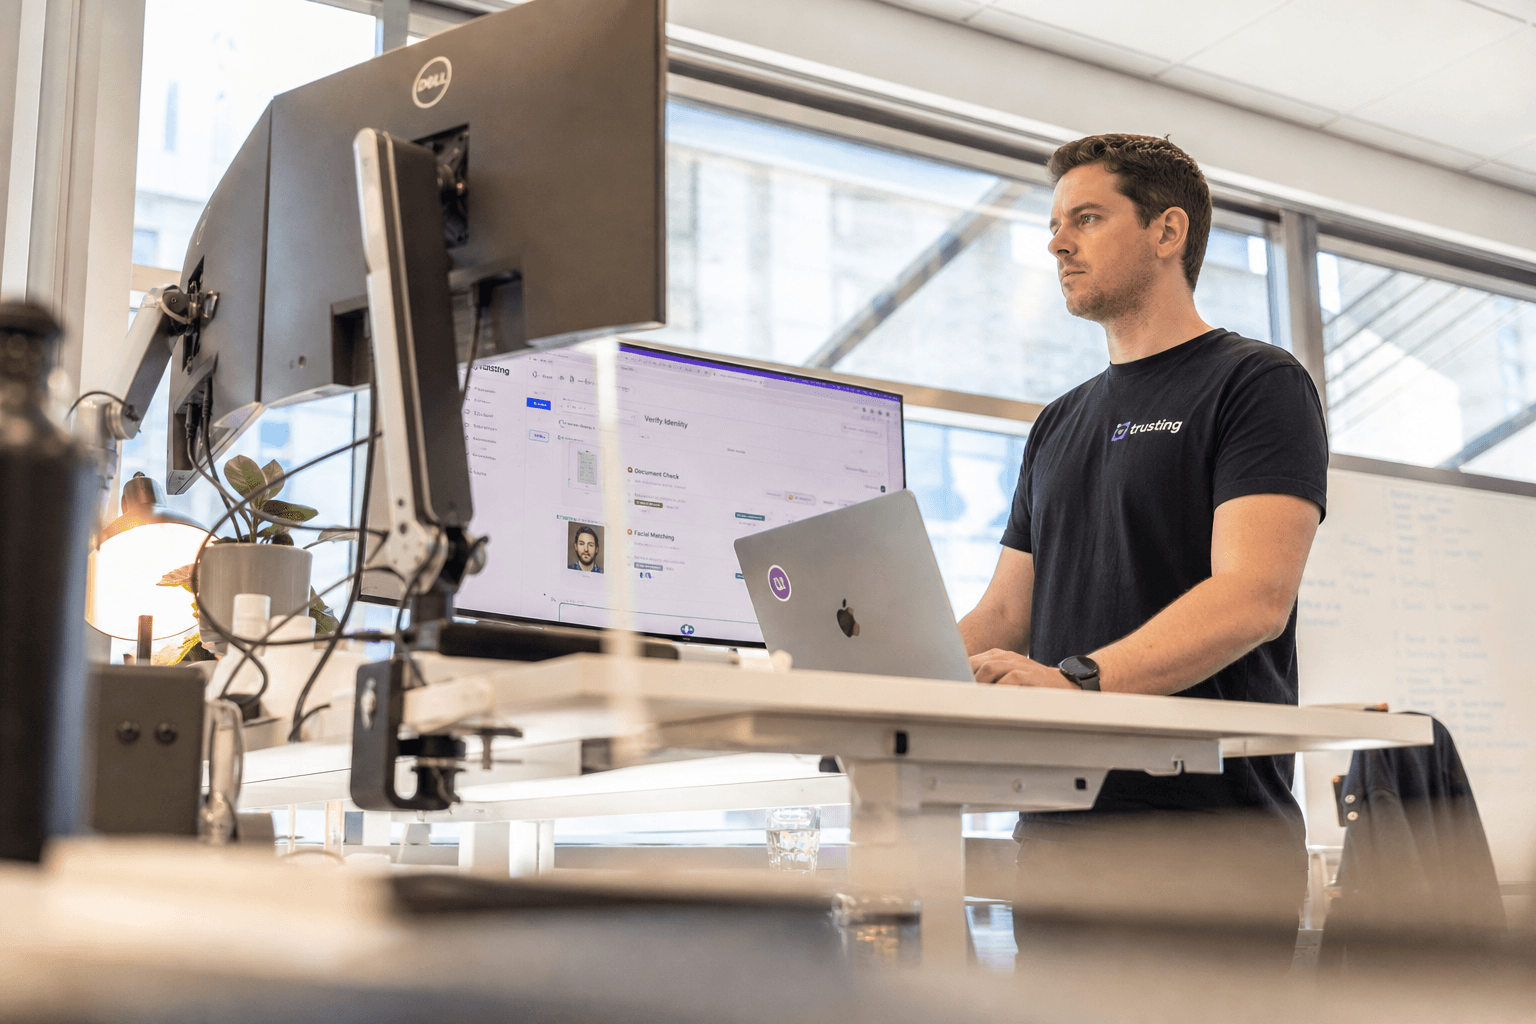
Digital identity verification is the process of confirming that a customer is who they claim to be, using document checks, biometric matching, and database cross-referencing instead of in-person verification. AI adds pattern recognition and automation to this process — reading identity documents, matching selfies to photo IDs, and flagging anomalies faster than a manual reviewer can. For Australian fintechs, this sits at the front door of every new account: get it wrong and you either block good customers or let bad actors through.
How does KYC/AML automation work during onboarding?
KYC (Know Your Customer) and AML (Anti-Money Laundering) automation chains together several checks — document authenticity, liveness detection, sanctions and politically exposed person (PEP) screening, and risk scoring — into a single onboarding workflow. AI models typically handle the first pass: extracting data from an uploaded ID, verifying it against issuing-authority formats, and scoring the likelihood of fraud or forgery. The output is a risk tier, not a final decision. Low-risk customers can move through with minimal friction; medium- and high-risk cases route to additional checks or a human analyst.
This is where the technology choice matters. A brittle, rules-only system creates onboarding drop-off; a well-designed AI layer — built on solid data-infrastructure and properly monitored models — reduces friction for genuine customers without quietly lowering your compliance bar. We've written more on the trade-offs between automation and oversight in our insights, including the question of when to build AI capability in-house versus when to bring in specialist support.
What are AUSTRAC's obligations for AI-assisted KYC/AML?
AUSTRAC is Australia's financial intelligence and AML/CTF regulator, and every reporting entity under the Anti-Money Laundering and Counter-Terrorism Financing Act 2006 — including most fintechs offering designated services — must have a documented AML/CTF program, conduct customer identification (the KYC step), perform ongoing customer due diligence, and lodge suspicious matter reports (SMRs) and threshold transaction reports (TTRs) where relevant. Automating parts of this process does not remove these obligations — it changes how you evidence them.
If an AI model is making or materially influencing a KYC decision, your AML/CTF program documentation needs to explain what the model does, how it's monitored, and who is accountable when it gets something wrong. AUSTRAC guidance and the broader Australian AI governance context — including the Department of Industry, Science and Resources' Voluntary AI Safety Standard and Guidance for AI Adoption — point in the same direction: AI systems in regulated contexts need clear ownership, auditability, and a documented human-in-the-loop process, not just good model performance. Fintechs should also track the ongoing Tranche 2 AML/CTF reforms, which are expanding reporting-entity obligations across the sector.
How should fintechs manage false positives in AML screening?
False positives in sanctions and PEP screening are an operational cost, not just a technical nuisance — every flagged customer who isn't actually a match consumes analyst time and creates friction in your onboarding funnel. Managing this well means tuning match thresholds deliberately, using fuzzy-matching logic that accounts for name variations and transliteration, and feeding analyst decisions back into the system so it learns which flags were genuine.
The goal is not to eliminate false positives entirely — a model tuned to zero false positives will also miss true matches — but to get the balance right for your risk appetite and to keep a clear audit trail of why each case was escalated or cleared. This is model engineering work as much as compliance work, and it benefits from the same MLOps discipline you'd apply to any production model: monitoring for drift, versioning thresholds, and testing changes before they hit live onboarding traffic.
Where does human review remain mandatory?
Human review remains mandatory wherever a decision carries genuine legal, financial, or reputational weight that an automated system cannot fully account for. In practice, that means: confirmed or ambiguous sanctions/PEP matches, suspicious matter report decisions, enhanced due diligence for high-risk customers, and any case where the AI model's confidence score falls below an agreed threshold. AUSTRAC does not permit fully automated SMR lodgement decisions without human sign-off, and most fintechs' own risk frameworks require an analyst to review and approve edge cases before an account is opened or restricted.
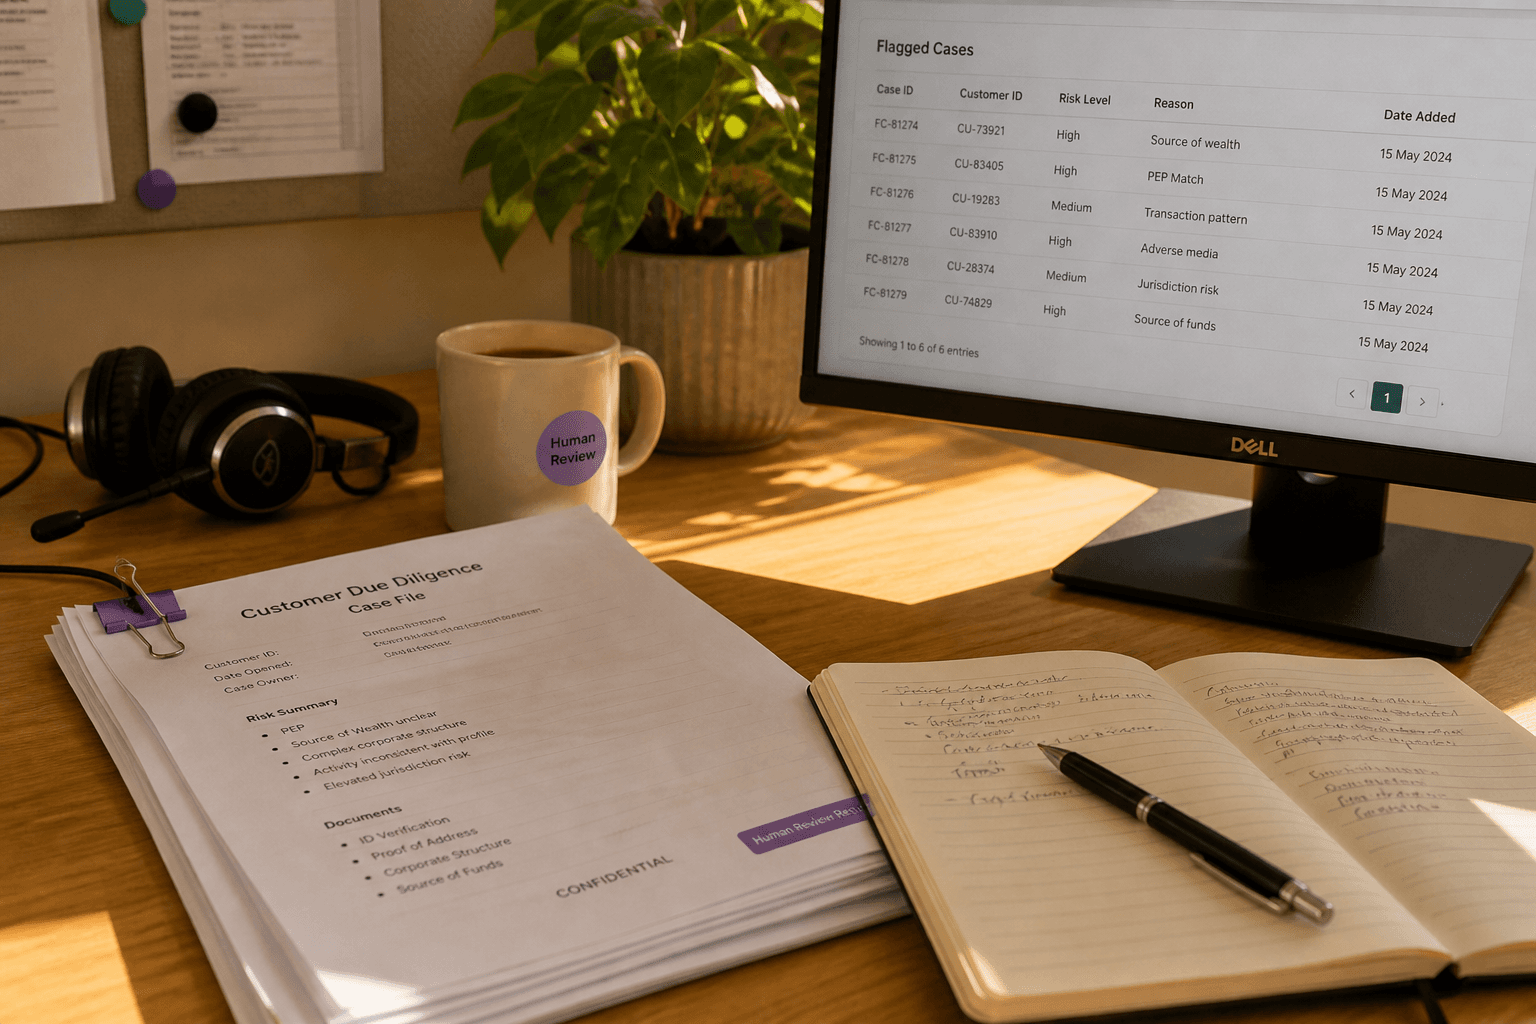
The practical design pattern is a tiered review model: AI handles routine, low-risk verification end-to-end; everything else is escalated with the AI's reasoning and supporting evidence attached, so the human reviewer can make a faster, better-informed decision rather than starting from scratch.
Manual vs AI-assisted KYC/AML onboarding
| Aspect | Manual-only process | AI-assisted process |
|---|---|---|
| Document verification speed | Slower, analyst-dependent | Faster for standard document types |
| Consistency of checks | Variable across analysts | More consistent, rules applied uniformly |
| Handling of edge cases | Relies on analyst judgement throughout | Routed to analyst with supporting context |
| Audit trail | Depends on analyst documentation habits | Can be systematically logged and versioned |
| Scalability during growth | Requires proportional headcount growth | Scales onboarding volume with less added headcount |
| Risk of undetected bias or drift | Lower (human judgement each time) | Requires active monitoring to manage |
Neither column is universally "better" — the right mix depends on your risk profile, customer volume, and regulatory exposure. Most Australian fintechs land on a hybrid: AI for volume and consistency, humans for judgement and accountability.
Building this responsibly
AI-assisted KYC/AML only works if it's built on top of reliable data foundations and clear product strategy — not bolted onto a legacy onboarding flow as an afterthought. That typically means addressing data-infrastructure gaps first (clean, well-governed customer and transaction data), defining the right human-in-the-loop model through ai-product-strategy, and then implementing the verification and screening logic through disciplined ai-engineering that includes monitoring, versioning, and audit logging from day one.
For fintechs still running onboarding through an ageing core system, this is often also an application-modernisation problem — you can't layer AI-assisted compliance checks cleanly onto a monolith that wasn't designed for it.
If you're exploring how to automate identity verification or KYC/AML checks in your onboarding flow without compromising on compliance, we can help — get in touch and we'll talk through where automation fits and where human review needs to stay.
Chris Kerr
Partner at Horizon Labs, an AI product consultancy and venture studio. A commercially focused product and technology leader with 20+ years building and scaling digital platforms, teams, and businesses across SaaS, travel, eCommerce, logistics and transport, and digital marketing — operating at the intersection of product, engineering, and data. Writes about platform strategy, AI transformation, modern data ecosystems, and the operational discipline that separates AI demos from AI products.