AI Credit Scoring & Trade Finance Underwriting: A Practical Guide
This is a placeholder
B2B fintech lenders are under pressure to underwrite faster without taking on hidden risk. Machine learning can help — but credit risk scoring and trade finance underwriting are high-stakes, regulated decisions, and a model that can't explain itself is a liability, not an asset. This guide is for engineering and risk teams building or buying these systems in Australia.
What is AI-assisted credit risk scoring for B2B lenders?
AI-assisted credit risk scoring is the use of statistical or machine learning models to estimate the probability that a business borrower will default, alongside traditional credit assessment. For B2B lenders, this typically means supplementing (not replacing) financial statement analysis, director guarantees, and bureau data with models trained on transaction history, cash flow patterns, and alternative data signals. The goal is a faster, more consistent decision — not a black box that quietly makes the call for you.
Why is trade finance underwriting different from consumer credit scoring?
Trade finance underwriting assesses risk at the transaction level — a specific shipment, invoice, or purchase order — rather than just the borrower level. It has to account for counterparty risk (the buyer paying the invoice), goods or commodity risk, country and currency exposure, and document integrity (bills of lading, letters of credit, customs documentation). Consumer credit scoring rarely deals with any of this.
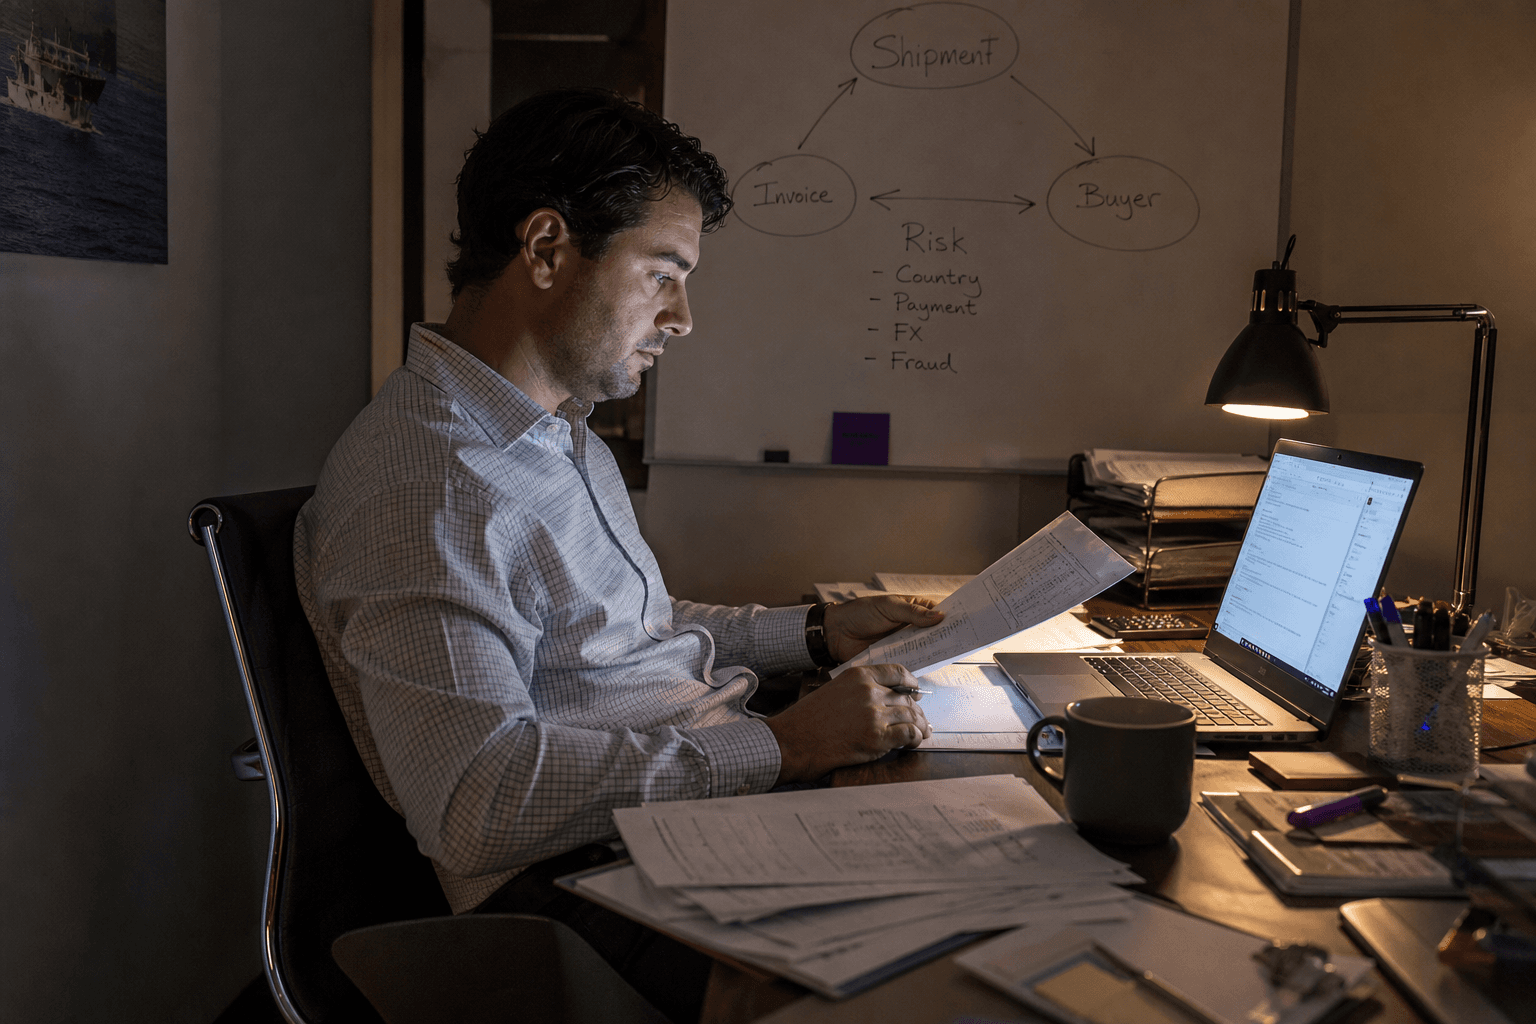
This means trade finance models need different feature sets: buyer concentration and payment history, industry and trade-lane risk, invoice or PO verification signals, and sometimes satellite or shipping data for physical goods tracking. A model built for working capital loans won't transfer cleanly to invoice finance or supply chain finance without rework.
What data sources support credit risk models for business lending?
Credit risk models for B2B lending draw on a mix of structured financial data, transactional data, and alternative signals. Structured sources include bureau reports, ATO and ASIC filings, accounting software feeds (via open banking or direct integration), and bank transaction data. Alternative signals — trade references, e-invoicing platforms, marketplace or payment processor data — can improve signal for thin-file borrowers, but each new source adds a data quality and governance burden.
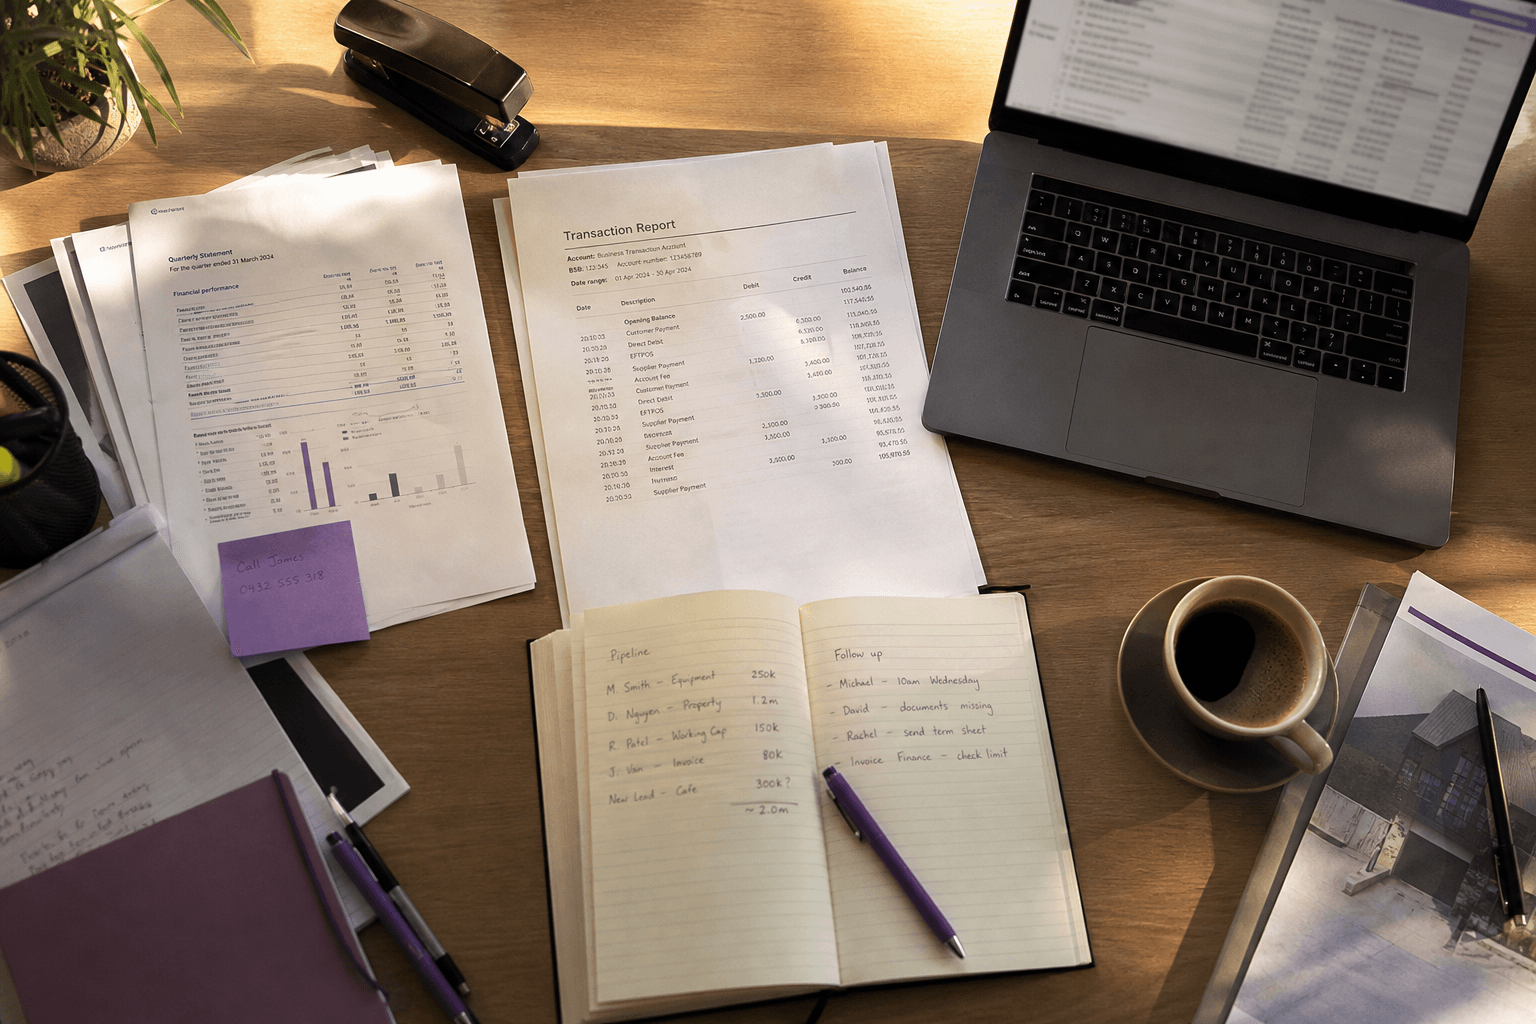
Before any of this reaches a model, it needs to be ingested, validated, and reconciled against a single borrower identity — which is fundamentally a data infrastructure problem before it's a modelling problem. Lenders who skip this step tend to find their model performance is actually a data pipeline problem in disguise.
How much model explainability do risk teams actually need?
Risk teams need enough explainability to justify a decline, support an internal audit, and respond to a borrower dispute — in plain language, not SHAP values alone. That typically means every scored decision should produce a small set of human-readable reason codes (e.g.
Chris Kerr
Partner at Horizon Labs, an AI product consultancy and venture studio. A commercially focused product and technology leader with 20+ years building and scaling digital platforms, teams, and businesses across SaaS, travel, eCommerce, logistics and transport, and digital marketing — operating at the intersection of product, engineering, and data. Writes about platform strategy, AI transformation, modern data ecosystems, and the operational discipline that separates AI demos from AI products.